
By Aksana Tupalskaya | August 23, 2026
Quick Answer
What is a short sale on Oahu, and why do they take so long?
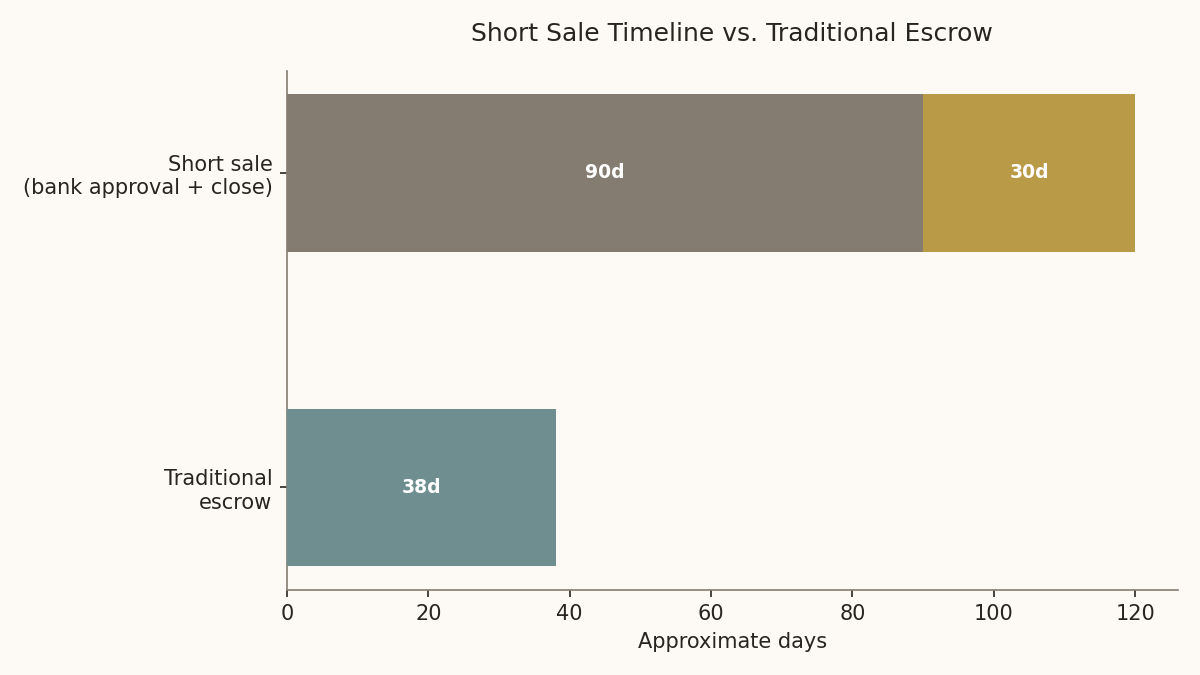
A short sale happens when a homeowner sells for less than what’s owed on the mortgage, with the lender agreeing in advance to accept the shortfall. They take a long time because the lender, not the seller or buyer, controls the pace: expect roughly 90 days for the bank to review and approve an accepted offer, then another 30 days or so to actually close, compared to a standard 30-45 day escrow when no lender approval is required.
Why the bank, not the seller, sets the pace
In a traditional sale, once a seller accepts an offer, the timeline is mostly about inspections, financing, and appraisal, typically 30 to 45 days start to finish. A short sale adds an entirely separate approval process: the lender has to review the seller’s financial hardship documentation, order its own valuation of the property, and decide whether to accept less than the full loan balance. That internal review commonly takes around 90 days on its own, before the deal can move toward closing.
This is the part sellers and buyers both underestimate. It’s not that short sale paperwork is more complicated to fill out, it’s that a third party with its own internal timeline, workload, and risk committee has to sign off before anything else can proceed.
Gain is not equity, and that surprises short sale sellers too
It’s a common assumption that a short sale means no tax consequences, since the seller is walking away with nothing or even owing money after the fact. That’s not automatically true. Hawaii’s Department of Taxation has published a worked example showing a seller with zero equity who still had a $203,182 taxable gain, most often the result of an earlier cash-out refinance that reduced equity without reducing the property’s cost-basis math the same way. [SOURCE: State of Hawaii Department of Taxation, Tax Facts 2010-1, revised April 2025]
Short sales are still dispositions of property for HARPTA purposes, so the standard 7.25% withholding applies unless reduced through Form N-288B based on the seller’s actual numbers. Given how tight short sale proceeds already are, this is worth addressing with a CPA before closing, not after.
| Stage | Traditional Escrow | Short Sale |
|---|---|---|
| Time to close after accepted offer | 30-45 days | Roughly 120 days total (about 90 for bank approval, then 30 to close) |
| Who controls the pace | Buyer’s financing and inspection timeline | The lender’s internal approval process |
| HARPTA withholding | Applies at 7.25% unless exempted | Applies the same way; N-288B can reduce it if proceeds are insufficient |
What this tells me as the numbers agent for Oahu sellers: the extra time in a short sale sits almost entirely in one place, the bank’s approval, which is exactly why setting expectations with a buyer upfront about that stretch matters more than anything else in the process.
What actually helps a short sale move faster
The seller’s own paperwork is the one part of this process within their control, and getting it complete and accurate on the first submission avoids the most common cause of extra delay: the lender kicking the file back for missing documentation and restarting the clock. Beyond that, patience with the buyer is worth setting expectations on early, since a buyer who doesn’t understand why 90 days of silence is normal is more likely to walk away mid-process.
Early occupancy and rent-back options while a short sale is in process
In some cases, it’s possible to negotiate early occupancy for the buyer before the short sale actually closes. This comes up most often with military buyers, who don’t always have 120 days of flexibility to wait on a lender’s approval before they need to be in a home. Depending on the seller’s timeline and the lender’s terms, it can be structured so the buyer moves in early and pays rent to the seller while the short sale continues working through approval.
This isn’t automatic, and it depends on what the seller is able and willing to agree to, along with the specifics of the lender involved. But the options exist, and they’re worth discussing early rather than assuming a long approval timeline is a hard stop for a buyer on a tight PCS clock. Reach out and I can walk through what might be possible for your specific timeline.
I also work with short sale facilitators who specialize in negotiating directly with lenders, which tends to keep the file moving and helps prevent the kind of back-and-forth that resets the approval clock. If there’s any chance your Oahu sale will need to go the short sale route, the best time to start that process, and to get the actual numbers calculated, is as early as possible, not after an offer is already in hand.
Frequently Asked Questions
Does HARPTA still apply to a short sale?
Yes. A short sale is still a disposition of property, so HARPTA withholding applies the same as any other sale. Because short sale proceeds are often insufficient to cover the withholding, Form N-288B can reduce or eliminate it based on the actual numbers.
Can a short sale close faster if I have a backup offer ready?
Not usually. The bottleneck is the lender’s internal review process, not the number of offers you present. A backup offer can help if the first buyer walks away, but it doesn’t shorten the bank’s approval timeline.
Is a short sale the same as a foreclosure?
No. In a short sale, the owner is still selling the property voluntarily, with the lender agreeing to accept less than the full loan balance. A foreclosure is the lender taking the property after the owner stops paying. They have different processes and different outcomes for the seller’s credit.
Can a buyer move into the home before a short sale closes?
Sometimes, yes. It’s possible to negotiate early occupancy with the buyer paying rent to the seller while the short sale is in process, depending on the seller’s timeline and the lender’s terms. This comes up most often with military buyers who don’t have months of flexibility before they need to be in a home. Reach out and we can talk through what might work for your situation.
If there’s a chance your Oahu sale could end up needing to go the short sale route, the best move is starting early, getting the real numbers calculated, and looping in a short sale facilitator before an offer is already on the table. Book a free 20-minute strategy call here, or read more on what out-of-state owners should know about HARPTA here.



