

Quick Answer
DTRIC is leaving Hawaii. When does it affect my homeowners policy?
Homeowners non-renewals begin with policies whose anniversary dates fall in November 2026, and the exact date is still to be determined. Your renewal date is your deadline, not the announcement date. If DTRIC writes your policy and your anniversary is in November or December, start shopping now rather than waiting for a notice.
By Aksana Tupalskaya | October 30, 2026
This one has a date on it, which is why it is worth five minutes today instead of five minutes in December.
What is actually happening, and the one date that matters for homeowners
On October 1, 2025, DTRIC announced its decision to exit the Hawaii insurance market. The Hawaii Insurance Division has kept a plain language page on it since, and that page is the only source I would trust for dates, because the dates have been published in stages rather than all at once. You can read it at the Insurance Division’s DTRIC exit FAQ.
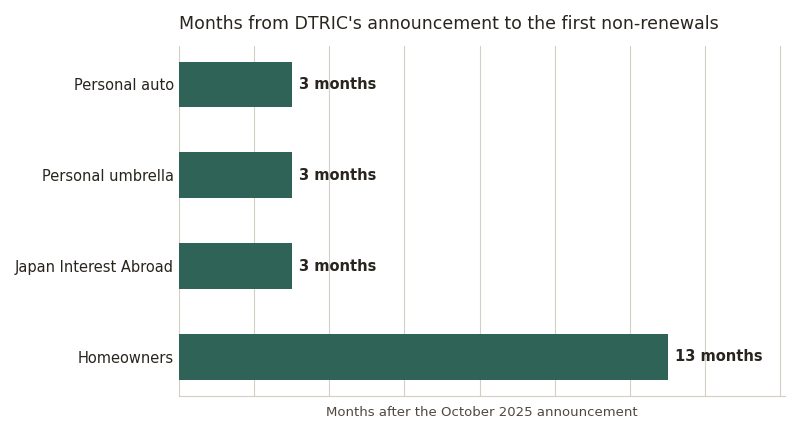
The line that matters to a homeowner: non-renewals for homeowners policies begin with anniversary dates occurring in November 2026, and the Division notes the exact date is still to be determined. Personal auto and personal umbrella are already further along, with non-renewals beginning on anniversary dates on or after January 2, 2026, and DTRIC planning to send a non-renewal notice sixty days before the policy expires.
Two things that should lower the temperature. Your policy does not vanish when the company announces an exit: a policy reaching its anniversary before its non-renewal date renews as usual for its full term. And on claims, the Division says DTRIC will remain in Hawaii to ensure claims occurring during the in-force policy period are settled or closed, and will keep processing claims in the ordinary course until the last one is completed.
| Line of business | Non-renewals begin with anniversary dates | Notice the Division describes | Source |
|---|---|---|---|
| Homeowners | In November 2026, exact date still to be determined | Not stated on the Division’s page | Hawaii Insurance Division, DTRIC exit FAQ |
| Personal auto | On or after January 2, 2026 | A non-renewal notice sixty days before the policy expires | Hawaii Insurance Division, DTRIC exit FAQ |
| Personal umbrella | On or after January 2, 2026 | A non-renewal notice sixty days before the policy expires | Hawaii Insurance Division, DTRIC exit FAQ |
| Japan Interest Abroad | On or after January 2, 2026 | Not stated on the Division’s page | Hawaii Insurance Division, DTRIC exit FAQ |
What this tells me working with Oahu homeowners: auto was the warning shot and homeowners is the one carrying a November date, so whoever shops in October is choosing from a market the December crowd will not have.
Why the renewal date is the deadline, not the announcement
Here is the practical problem with waiting for a notice. A non-renewal notice tells you that your coverage ends on a date you already knew, and it arrives when the replacement market is busiest with everyone else who also waited. On an island with a limited number of carriers writing homeowners business, the order you arrive in matters.
So the useful move is small and it is this: find your policy, read two lines on it, the carrier name and the renewal date. If the carrier is DTRIC and the renewal is in November or December, call your agent this month and ask them to quote replacement coverage now. If the carrier is someone else, you have learned your renewal date, which is worth knowing anyway.
The Division’s own guidance is the same, in fewer words: work with your insurance agent to find replacement coverage for your DTRIC policy. It also points homeowners who cannot get private coverage to the Hawaii Property Insurance Association, and publishes premium comparison charts and a license lookup so you can check that whoever quotes you is licensed here. The Insurance Division can be reached at (808) 586-2790.
If you own a condominium rather than a house, your exposure here is different and probably smaller, because the building’s master policy carries the structure and your own policy covers a narrower slice. I went through where that line sits in HO-6 insurance versus the building’s master policy, and the separate state fund built for condo associations in this post on the condo insurance relief fund.
If you are selling or buying in the next few months
This is where an insurance question stops being an insurance question and becomes a closing question.
A lender will not fund without evidence of hazard insurance in place at closing. That is standard everywhere, and it means a buyer who cannot get a policy bound cannot close on schedule, however clean the rest of the file is. When a carrier is withdrawing from a market, the insurance step quietly moves from a formality to a real item on the timeline.
If you are listing in the next couple of months, three things are worth doing before you are in escrow. Know what your own coverage situation is, so a buyer’s question does not get a vague answer. Tell your agent early if your carrier is one of the ones withdrawing, because it affects how the insurance contingency should be timed. And if the property is a condominium, have the association’s current master policy declaration page available, because that is the document a buyer’s insurer will ask for and it is slow to get at the last minute.
If you are buying, get a quote during your inspection window rather than after it. A quote is free, it takes a phone call, and it is the cheapest way to find out early that a particular building or a particular roof age is going to be a problem.
I am a real estate agent, not an insurance producer, and I cannot quote you or tell you what your premium will be. What I can tell you is where this shows up in a transaction, and that is usually about ten days before closing, when it is late to be learning it.
Frequently Asked Questions
Is my DTRIC homeowners policy cancelled right now?
No. This is non-renewal, not cancellation. The Insurance Division’s examples show a policy reaching its anniversary before its non-renewal date renewing as usual for its full term. For homeowners policies, non-renewals begin with anniversary dates in November 2026.
Will DTRIC still pay a claim if something happens before then?
Per the Insurance Division, DTRIC will remain in Hawaii to ensure claims occurring during the in-force policy period are settled or closed, and will continue processing claims in the ordinary course until the last claim is completed. If you have a claim question specific to your policy, call your agent or the Division.
What if no private carrier will write my house?
The Division points homeowners in that position to the Hawaii Property Insurance Association, which exists for exactly this situation. Start with your agent and the Division’s premium comparison charts first, because the association is the fallback rather than the first stop.
Does this change what my house is worth?
Not by itself. What carrier availability changes is the cost of holding a property and occasionally the speed of a closing, and those show up in a buyer’s math rather than in an assessed value. If you want to know what is actually happening to prices near you, use real closed sales rather than a single headline.
On that last point: if you want the actual sold data near you, including the seller credits the portals never show, I publish it monthly for four Oahu regions and you can get it at islandlivingoahu.com/credits. In the August closings I track, 54 of 230 sales carried a seller credit and the largest single one was $85,000. That is the kind of number that moves a decision, and it is not on any portal.


