
Quick Answer
Can you keep a parent’s mortgage rate on an Oahu home you inherited?
Yes. A federal law called the Garn-St Germain Act lets you, as the heir, keep making payments on the existing loan at its original rate instead of being forced to refinance or pay it off, even though most mortgages contain a due-on-sale clause. The lender cannot call the loan due simply because the owner died and the property passed to you by will, trust, or intestate succession.
You do still need to contact the loan servicer and ask to be recognized as what federal rules call a successor in interest. The protection is automatic under the law, but the paperwork that keeps your payments on track is not.
By Aksana Tupalskaya | October 21, 2026
Why the Loan Doesn’t Automatically Come Due
Most mortgages, on Oahu and everywhere else, contain a due-on-sale clause: language that lets the lender demand the full balance the moment the property changes hands to someone new. Without an exception, inheriting a house would also mean inheriting a bill you could not actually keep paying the way the person before you did.
The exception is federal, not something Hawaii had to write on its own. The Garn-St Germain Depository Institutions Act of 1982, codified at 12 U.S.C. Section 1701j-3(d), blocks a lender from enforcing a due-on-sale clause when the transfer happens because the borrower died and the property passes to a relative who occupies it, or into a living trust where the original borrower remains the beneficiary, along with a short list of other family transfers.
Loan servicers also operate under Consumer Financial Protection Bureau rules that require them to work with you once you can show an ownership interest in the property, a status the CFPB calls a successor in interest. This is not a favor a lender grants you. It is a right, and a servicer that tries to accelerate the loan or refuses to communicate with you because you were not the original borrower is doing something the CFPB has specifically written rules against.
What You Actually Have to Do to Keep It
The law protects the loan. It does not file the paperwork for you. Once you have the authority to act, whether that is letters from the probate court, a trust document, or simply being the surviving joint owner, the practical steps look like this:
- Contact the loan servicer in writing as soon as you reasonably can, and identify yourself as the person who inherited the property.
- Provide a copy of the death certificate and documentation showing your ownership interest, such as letters of personal representative or the recorded deed.
- Ask specifically to be confirmed as a successor in interest under Regulation X, which is the formal status that lets the servicer speak with you and keep the loan current without requiring you to qualify financially just to get information.
- Keep making payments on the existing schedule while this is being processed, even before the servicer has formally updated its records, so the loan does not slip into default.
- Update the homeowner’s insurance policy to list you, and if you plan to live in the home yourself, look into filing your own property tax home exemption rather than assuming the seller’s exemption carries over automatically.
If you want the loan fully assumed into your name alone, removing the original borrower from the note entirely, some lenders will ask for a formal assumption agreement, and that step can involve a credit review. That is a different, optional step from the successor-in-interest protection, which applies regardless of your credit.
When Keeping the Loan Beats Refinancing or Selling
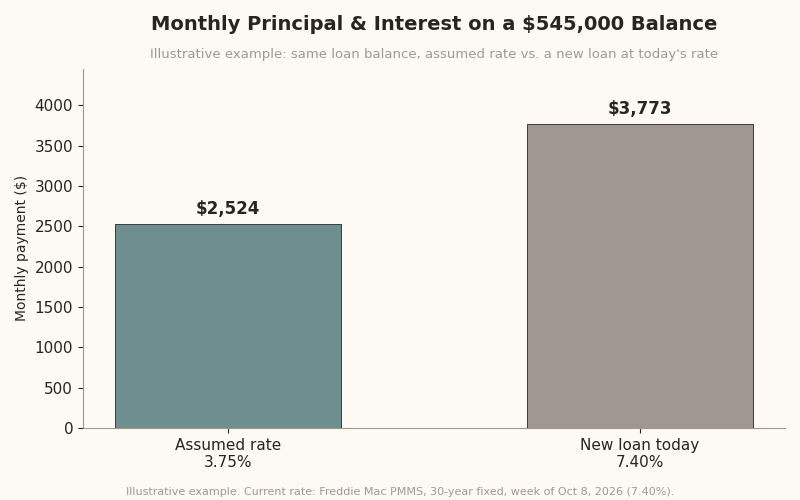
The reason this matters right now is the gap between old rates and new ones. On a $545,000 balance, keeping a loan at 3.75 percent runs about $2,524 a month in principal and interest. Refinancing that same balance into a new loan at today’s rate, 7.40 percent as of Freddie Mac’s survey for the week of October 8, 2026, runs about $3,773 a month, roughly $1,249 more every month for borrowing the exact same amount.
That gap is why many heirs choose to keep the loan rather than refinance, even when what they would really prefer is cash. The rate itself has real value, separate from the house. One caveat: Garn-St Germain protects the loan, not an automatic right to the whole property. If you have siblings or co-heirs and only you want to keep the house, you generally still need to buy out their share of the equity, either in cash or through a separate loan of your own.
If You’d Rather Sell, the Rate Still Matters
If the estate decides to sell instead of keep the home, the type of loan on title still matters. FHA, VA, and USDA loans are assumable by a qualified buyer, so an inherited Oahu property carrying one of these loans at a well-below-market rate can be marketed as an assumable listing, which widens the buyer pool considerably. I walk through exactly how that works, including the paperwork and the cash-to-close math, in how to take over a seller’s low-rate mortgage on Oahu.
Conventional loans are usually not assumable by an unrelated buyer, but Garn-St Germain still protects you as the heir in the meantime, while the estate decides what to do. And if you live out of state and the sale goes through, HARPTA withholding applies to the amount realized regardless of how little actual gain exists after the step-up in basis. I cover that trap in detail in HARPTA on inherited Oahu property.
| Option | What It Costs You | What It Requires |
|---|---|---|
| Keep the loan (Garn-St Germain) | Payment stays at the original rate | Notify the servicer, provide the death certificate and proof of your ownership interest, request successor-in-interest status |
| Refinance into your own name | Payment resets to today’s rate | Full underwriting, an appraisal, and closing costs, the same as any new loan |
| Sell with the loan in place | No ongoing payment, but you give up the rate | If it’s FHA, VA, or USDA, a buyer may be able to assume it instead of getting a new loan |
What this tells me as the agent heirs usually call first: the loan on title is not automatically a bill you have to refinance away, and in a rate environment like this one, it is often the most valuable thing left in the estate.
Frequently Asked Questions
Does the lender have to approve me taking over the loan?
No approval is required for the type of transfer Garn-St Germain protects, which includes a transfer by inheritance to a relative who occupies the property. You do need to contact the servicer, provide documentation, and request successor-in-interest status so your payments and communications stay on track.
What if there are multiple heirs and only one of us wants the house?
The heir who keeps the house generally needs to buy out the other heirs’ share of the equity, either in cash from other estate assets or through a loan of their own. Garn-St Germain protects the existing loan from being called due; it does not resolve who owns what share of the property.
Does this protection apply to every type of loan?
Yes, the death-and-inheritance exemption in Garn-St Germain applies broadly to residential mortgages regardless of whether the loan is conventional, FHA, VA, or USDA. FHA and VA loans also have their own separate assumption procedures if you want the loan formally transferred into your name.
What if the mortgage was already behind on payments when the owner died?
Garn-St Germain protects the loan from being called due because of the transfer, but it does not erase any payments that were already missed. Once title passes to you, resolving any existing default becomes your responsibility, and this is a good moment to talk with a probate attorney about your options.
What to Do Next
Inheriting an Oahu house with a mortgage still attached is rarely as simple as either keep it or sell it. It usually depends on who else has a stake in the estate, what the loan’s rate actually is, and what you and any co-heirs actually want long term. A probate attorney can confirm where things stand with the court process, and I’d recommend talking with one before you make a final call.
If you are trying to work out whether keeping the loan, refinancing, or selling makes the most sense for your specific situation, that is exactly the kind of conversation I have with out-of-state heirs regularly. Book a free 20-minute strategy call and I will walk through your numbers with you: islandlivingoahu.com/strategy.



