
Of everything available to a veteran who bought a home on Oahu, this is the one with the biggest dollar figure attached and the lowest awareness. The VA Office of Inspector General has already confirmed that more than 250 veterans were owed funding fee refunds between October 2021 and September 2024 and had not claimed them.
Quick Answer
Can veterans get the VA funding fee refunded after buying an Oahu home?
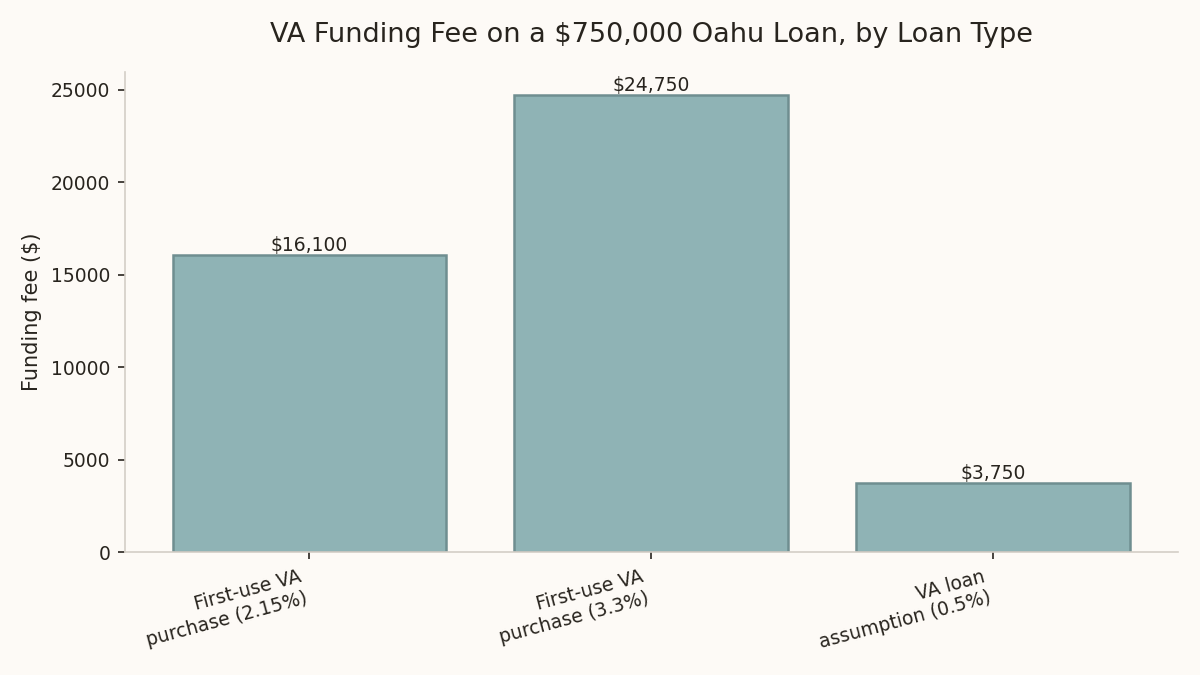
Yes, if your VA disability compensation award is effective on or before your loan’s closing date, you should not have been charged the funding fee at all, and it is refundable. If your rating came through after closing but is retroactive to a date before closing, the fee is still refundable. On a $750,000 Oahu loan, a first-use funding fee runs roughly $16,100 to $24,750 depending on your down payment. The VA never sends this refund automatically. You have to request it directly through the VA Regional Loan Center.
By Aksana Tupalskaya | September 12, 2026
| Loan type / scenario | Funding fee rate | Approximate fee on $750,000 | Refundable? |
|---|---|---|---|
| First-use VA purchase, no exemption | 2.15% | ~$16,100 | Yes, if disability rating is effective on or before closing (or retroactive to before it) |
| First-use VA purchase, no exemption (higher tier) | 3.3% | ~$24,750 | Same as above |
| VA loan assumption | 0.5% | ~$3,750 | For comparison — a materially smaller fee than a new VA purchase loan |
| Veterans who never claimed a refund they were owed | — | 250+ identified | VA Office of Inspector General, refunds owed Oct 2021–Sept 2024 |
What this tells me as the numbers agent for Oahu buyers: this is the single largest refundable dollar figure available to the military audience on this island, and the VA Office of Inspector General has already confirmed hundreds of veterans left it unclaimed.
Who this actually applies to
The VA funding fee is a one-time charge added to most VA-backed purchase loans, typically 2.15 percent to 3.3 percent of the loan amount on a first-use purchase, depending on down payment. Veterans receiving VA disability compensation are exempt from paying it at all.
Two situations create a refund opportunity:
- Your disability rating was already effective on or before your closing date, but the fee was charged anyway, often because the paperwork had not caught up with the VA’s own system by the time you closed.
- Your rating came through after closing, but the VA made it retroactive to a date before your closing. Retroactive effective dates are common when a claim takes months to process but the VA backdates the award to an earlier date.
In either case, the fee should not have been charged, and it is refundable.
Why nobody tells you this
The refund is never issued automatically. Lenders collect the funding fee at closing and send it to the VA; nothing in that process re-checks a veteran’s exemption status after the fact unless the veteran initiates it. A rating that becomes effective or gets backdated after closing simply sits there, unconnected to a loan that already closed, unless someone calls and asks.
That single phone call is the entire mechanism: the VA Regional Loan Center, 1-877-827-3702.
What to have ready before you call
Three documents make this a fast conversation instead of a slow one:
- Your updated Certificate of Eligibility (COE) showing exempt status
- Your Closing Disclosure showing the funding fee that was charged
- Your VA disability award letter, specifically showing the effective date of the rating
The effective date on the award letter is the detail that matters most. If it falls on or before your closing date, or is backdated to a date before closing, you have a strong case for a refund.
The dollar figures, honestly stated
On a $750,000 Oahu loan, a first-use VA funding fee runs approximately $16,100 to $24,750, depending on the specific rate tier that applied to your loan. These are not promises of what any individual veteran will get back, since the exact refund depends on your own loan amount, funding fee rate, and effective date. It is simply the range that shows how large this can be relative to loans in this price range, which is common on Oahu.
For comparison, veterans assuming an existing VA loan instead of originating a new one pay a much smaller 0.5 percent funding fee, since assumption transfers an existing loan rather than creating a new one.
Frequently Asked Questions
How do I know if my VA disability rating is “retroactive” to before my closing date?
Your VA disability award letter states the effective date of your rating. If that date falls on or before your loan’s closing date, the rating is retroactive to before closing, even if the letter itself arrived months later.
Who do I actually contact to request the refund?
The VA Regional Loan Center, 1-877-827-3702. This is the direct line for funding fee refund requests.
Does this apply to VA loan assumptions too?
The assumption funding fee is already much lower, 0.5 percent versus 2.15 to 3.3 percent on a first-use purchase, so the refund opportunity described here is specifically about first-use purchase loans where a disability exemption applied but was not honored at closing.
Is there a deadline to request this refund?
This post does not state a specific deadline, since eligibility and timelines vary by individual case. Contact the VA Regional Loan Center directly to confirm your situation rather than assuming a window has closed.
If you know a veteran who bought on Oahu
Send this to them today, especially if their disability rating came through any time after they closed on their home. This is general information, not individualized guidance on your VA benefits; confirm your specific situation directly with the VA Regional Loan Center.
Curious what else is available to veterans and assumable-loan buyers on Oahu right now? Get the free biweekly list of Oahu homes with assumable low-rate loans here.



