
Quick Answer
Can you assume an FHA loan when buying a home on Oahu?
Yes. FHA loans are assumable, meaning a qualified buyer can take over the seller’s existing loan, including its interest rate, instead of getting a new loan at today’s rate. Unlike a VA loan, assuming an FHA loan does not require you to be a veteran or tie up anyone’s VA entitlement. You simply need to qualify with the lender the same way you would for a new FHA loan, through a standard credit and income review.
By Aksana Tupalskaya | October 27, 2026
Why FHA Assumption Gets Overlooked
Most of the conversation around assumable loans on Oahu, and nationally, centers on VA loans, largely because the entitlement story is unusual and worth explaining. I cover exactly how that works, including what happens to a seller’s entitlement when a non-veteran buyer assumes their VA loan, in can you assume a VA loan on Oahu as a non-veteran buyer.
FHA loans get far less attention despite being assumable under the same basic principle, and despite being originated more often nationally than VA loans. For a buyer who is not a veteran and was never going to be eligible for a VA loan in the first place, an assumable FHA loan is often the more directly relevant option sitting on the table, and it is worth knowing to ask your agent whether a listing’s existing loan is FHA before assuming it is out of reach.
How FHA Assumption Actually Works
Unlike the very old, pre-December 1986 “simple assumption” FHA loans that transferred with essentially no review, every FHA loan originated since then requires what is called a creditworthiness assumption. In practice that means:
- You apply to assume the loan through the seller’s existing lender, not a new lender of your choosing, since you are taking over their specific loan.
- The lender reviews your credit, income, and debt the same way it would for a new FHA loan application, not a lighter review.
- You cover the gap between the remaining loan balance and the purchase price in cash or through secondary financing, the same gap problem that applies to any assumable loan.
- Once approved, the lender formally substitutes you as the borrower and, with proper documentation, releases the seller from further liability on the loan.
That timeline runs on a similar clock to a VA assumption, commonly a few months rather than a few weeks, largely because you are waiting on the existing lender’s assumption department rather than a competitive mortgage shop processing a brand new loan. I walk through the full process, cash-to-close math, and a worked example on taking over a seller’s low-rate mortgage in how do you take over a seller’s low-rate mortgage on Oahu.
The Payment Math
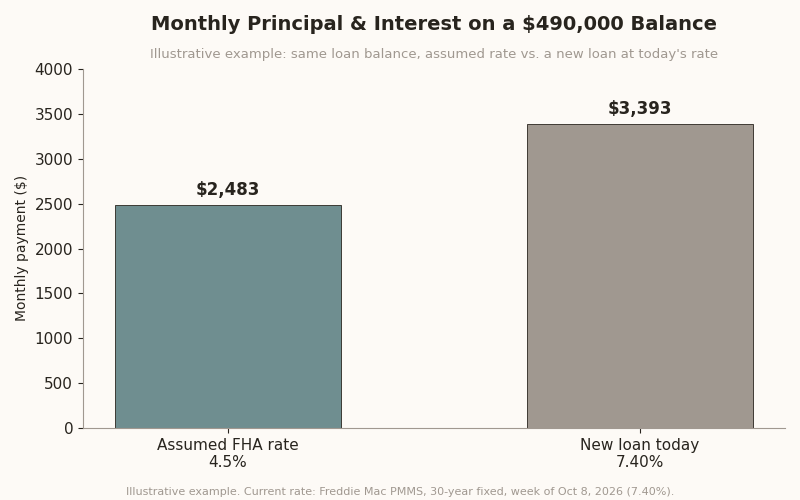
The appeal of assuming any older, lower-rate loan is the same regardless of loan type: you keep the rate instead of borrowing at today’s cost. On a $490,000 balance, assuming an FHA loan at 4.5 percent runs about $2,483 a month in principal and interest. A new loan on the same balance at today’s rate, 7.40 percent as of Freddie Mac’s survey for the week of October 8, 2026, runs about $3,393 a month, a difference of roughly $910 every month for borrowing the same amount.
The Same Gap Problem as VA Assumption
The math above only tells half the story, because you do not just take over the monthly payment, you also have to come up with the difference between the remaining loan balance and the purchase price in cash or a second loan at closing. If a home is listed at $650,000 and the assumable FHA balance is $490,000, that $160,000 gap, plus closing costs, is money you need at the table regardless of how attractive the assumed rate is. This is the exact reason a low remaining balance can actually shrink the pool of buyers who can realistically assume a loan, even though a low balance sounds like the better deal on paper. It is worth running this math on a specific listing before assuming an assumable loan automatically makes sense for your budget.
| Loan Type | Who Can Assume It | What Changes When Assumed |
|---|---|---|
| VA loan | Any qualified buyer, veteran or not | A non-veteran buyer ties up the seller’s VA entitlement until the loan is paid off; a VA buyer substituting their own entitlement restores the seller’s |
| FHA loan | Any buyer who qualifies with the lender’s credit and income review | No entitlement issue. The buyer simply qualifies the way any new FHA borrower would |
| Conventional loan | Generally not assumable | A due-on-sale clause typically requires payoff or refinance at sale, with narrow exceptions |
What this tells me working with Oahu buyers: FHA assumption solves the exact same rate problem VA assumption does, without needing anyone’s military eligibility, which is why it is worth checking on every listing, not just the ones marketed as VA-assumable.
Where This Shows Up Most on Oahu
FHA loans are common on Oahu condos and entry-level single-family homes, since FHA financing allows a lower down payment than many conventional programs and Hawaii’s FHA loan limits are set higher than the national baseline because the county is designated a high-cost area. That means an assumable FHA loan is realistically something you may run into on a wider range of price points here than you might expect from FHA’s reputation as a starter-home loan on the mainland. It is one more reason to ask the question on any listing, not just the ones already marketed as assumable.
Frequently Asked Questions
Does assuming an FHA loan require mortgage insurance?
Yes. FHA loans carry a mortgage insurance premium that generally continues with the assumption, and as the assuming buyer you take over those premium payments the same way the original borrower was making them.
How long does an FHA loan assumption typically take?
Plan on a similar timeline to a VA assumption, commonly framed as three to six months, since you are working through the existing lender’s assumption department rather than originating a new loan through a lender you chose competitively.
Can I assume an FHA loan if I am not a first-time homebuyer?
Yes. FHA assumption eligibility is about qualifying with the lender’s credit and income review, not about first-time buyer status. First-time buyer requirements apply to certain programs for originating a new FHA loan, not to assuming an existing one.
Is the seller fully released from the loan once it’s assumed?
With a proper lender-approved creditworthiness assumption, the seller is formally released from liability once the lender substitutes the new borrower. Sellers should always confirm that release in writing at closing rather than assuming it happens automatically.
Checking Whether a Listing Actually Has One
Not every listing advertises that its loan is assumable, and not every agent thinks to check. If you are shopping on Oahu and rate is a real part of your budget, it is worth asking directly whether a home’s existing financing is FHA or VA before ruling a listing out on price alone.
I keep a running list of Oahu homes with assumable loans, refreshed from MLS on the 1st and 15th of every month. Get on the list at islandlivingoahu.com/assumable-list.



